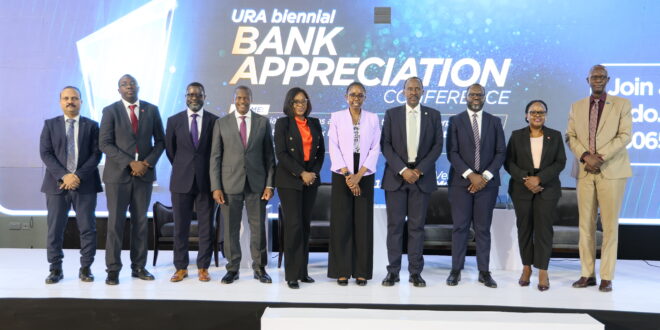
The Uganda Revenue Authority (URA) has called on the banking sector to demonstrate greater responsibility in meeting their tax obligations. John Rujoki Musinguzi, the Commissioner General, voiced concerns about the persistent issue of tax non-compliance, even as the financial sector continues to report healthy profits and deliver dividends to shareholders.
While many banks are thriving financially, their tax practices do not always reflect this success. Despite posting strong earnings, some institutions are still failing to fully meet their tax obligations, undermining the fairness of the tax system. This discrepancy is a growing issue, particularly when institutions with the ability to contribute more fall short in their duty to the nation.
Musinguzi pointed out that tax-related challenges such as delayed payments and unresolved disputes are persistent barriers to achieving full compliance. Some cases have lingered for years, creating uncertainty and inefficiencies in revenue collection. These delays have long-term impacts on national economic planning and resource allocation.
In addition to payment delays, incomplete tax disclosures from some institutions are further complicating efforts to ensure transparency and fairness. Full and accurate reporting is essential to tax compliance, yet some banks have not been as forthcoming as necessary, contributing to gaps in the system that make enforcement more difficult.
The Commissioner General emphasized that banks are not just accountable to their clients and shareholders, but to the country as a whole. Their role in the economy is crucial, and their commitment to proper tax practices is key to supporting national development. Financial institutions must contribute their fair share to the collective effort of building a prosperous nation.
Musinguzi also stressed the importance of collaboration between banks and tax authorities. Strengthening partnerships can help resolve disputes more efficiently and encourage a culture of mutual cooperation. By fostering better communication and understanding, both parties can ensure that compliance is both practical and sustainable.
As URA continues to enhance its enforcement efforts, Musinguzi reiterated that voluntary compliance is the best way forward. Banks should take proactive steps to align their operations with tax regulations, thereby avoiding penalties and contributing to the long-term health of the economy.
Ultimately, URA’s call is for a more accountable and transparent banking sector, where timely tax payments and full disclosures are the standard. By doing so, financial institutions can ensure they play a key role in fostering national growth and fairness, upholding their responsibilities to both their clients and the country at large.